
Crude Oil Surges Past $100 As RMB Hits 4-Year High, Testing Resilience Across The Global Textile Supply Chain
Nov 04, 2026
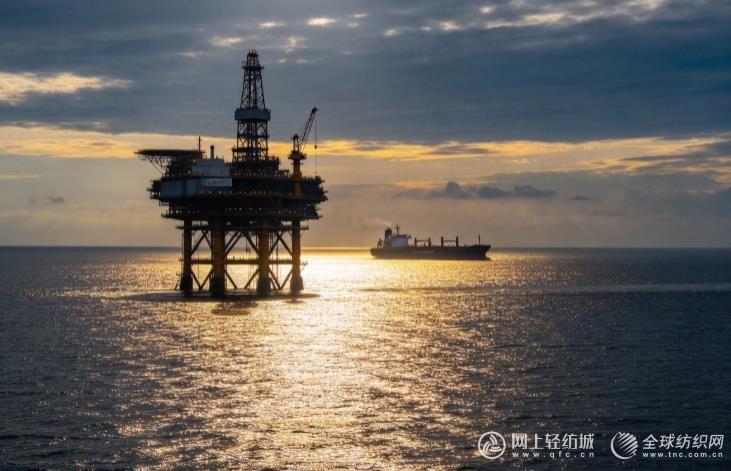
International crude oil prices experienced a sharp vertical rally, with Brent crude breaking past $107 USD per barrel and West Texas Intermediate (WTI) surging over the $97 USD per barrel barrier. Concurrently, the Renminbi (RMB) strengthened against the US Dollar, with onshore spot rates touching 6.6696 and offshore rates reaching 6.6688-marking a 4.6% year-to-date gain and setting a new peak since July 2022.
This dual economic landscape of "soaring crude oil costs alongside currency appreciation" presents complex cost-hedging and margin-protection challenges for export manufacturers across the Global Textile Supply Chain.
1. Upstream Petrochemical Transmission: OPEC+ Cuts and Depleted Inventories
The surge in crude oil benchmarks stems from fundamental supply constraints combined with geopolitical risk premiums:
- Supply Tightness and Production Controls: Sustained production cuts enforced by OPEC+ alliance members have contracted global crude oil availability, establishing a firm price floor.
- Depleted Global Inventory Reserves: Global crude reserves remain at historically low levels, removing buffer stock from physical spot markets. In an environment of depleted inventories, speculative buying accelerates upward price moves, amplifying volatility across downstream petrochemical feedstocks.
- Cost Transmission across Synthetic Fibers: Synthetic staple fibers-including polyester, nylon, and specialty acrylic alternatives-derive directly from petrochemical refining. Rising crude prices immediately inflate raw material quotes for Purified Terephthalic Acid (PTA), Monoethylene Glycol (MEG), and textile dyes, compressing operating margins for spinning, weaving, and dyeing operations.
2. Currency Dynamics: Import Cost Relief vs. Export Margin Compression
While rising crude oil prices drive up raw material expenses, the appreciation of the RMB creates contrasting effects across textile import and export operations:
Commodity & Foreign Exchange Impact Matrix
| Market Indicator | Current Financial Benchmark | Downstream Textile Industry Impact |
| Brent Crude Benchmark | Surpassed $107 USD / barrel. | Direct cost inflation for PTA, MEG, and synthetic yarns. |
| WTI Crude Benchmark | Crossed $97 USD / barrel. | Increases refining fuel surcharges and thermal processing overhead. |
| Onshore RMB Spot Rate | Reached 6.6696 per USD (+4.6% YTD). | Dilutes USD import costs for raw materials; reduces export revenue margins. |
| Offshore RMB Spot Rate | Reached 6.6688 per USD (4-year high). | Increases foreign exchange conversion risks on USD-denominated sales. |
Driven by strong trade surpluses and expanded foreign exchange settlement by export enterprises, currency appreciation provides a dual impact:
- Import Relief on USD-Denominated Feedstocks: For textile mills importing chemical raw materials, specialized synthetic staples, or machinery parts, a stronger local currency reduces USD purchasing expenses, partially offsetting raw petroleum price hikes.
- Margin Compression on Foreign Sales: For export-oriented apparel and fabric manufacturers operating under USD contract quotes, currency appreciation reduces local currency receipts upon conversion, placing immediate pressure on net export profits.
3. Financial Risk Mitigation and Supply Chain Adaptations
To navigate volatile energy markets and currency fluctuations, textile manufacturers are implementing proactive risk-management frameworks:
- Inventory and Hedging Flexibility: Spinning and weaving enterprises are adjusting raw material procurement schedules and establishing raw material safety stocks to cushion operations against sudden oil-driven price spikes.
- Foreign Exchange Risk Controls: Export-oriented textile mills are utilizing financial hedging tools-such as forward exchange contracts and currency options-to balance USD conversion risks while leveraging import cost advantages.
4. Material Upgrades to Buffer Petrochemical Volatility
To insulate manufacturing operations against persistent crude oil fluctuations and currency shifts, forward-thinking textile enterprises are upgrading material specifications:
- Decoupling from Virgin Petroleum Feedstocks: Transitioning from virgin petroleum polyester to GRS-certified Recycled Polyester Staple Fiber reduces direct exposure to volatile crude oil refining chains. Extruded from post-consumer PET bottle flakes, recycled polyester staple fiber delivers consistent linear density, high tensile strength, and reliable spinnability while lowering product carbon footprints.
- Cost-Stabilized Synthetic Fiber Alternatives: For knitwear and woven fabrics requiring soft thermal properties without the high cost volatility of natural wool or pure acrylics, specifying Bosilun staple fibers provides an economical alternative. Bosilun offers a soft tactile hand-feel, low pilling propensity, and excellent dye affinity, helping manufacturers elevate Material Performance, build Supply Chain Resilience, and execute adaptable Global Sourcing Strategies.
Industry Outlook and Trade Summary
The confluence of $107/barrel crude oil and a 4-year high RMB exchange rate underscores the need for structural adaptability within international trade. By combining financial foreign exchange risk management with functional fiber selections-such as Recycled Polyester Staple Fiber and Bosilun-textile manufacturers can buffer against upstream energy swings, protect export profitability, and maintain supply chain stability.
Leveraging our integrated cross-border supply chain network across China and Vietnam, we support global trade partners in securing certified synthetic fiber inputs, optimizing fabric cost structures, and executing effective Global Sourcing Strategies.


